Tax on Investments – What you need to know

Investors have to pay tax when they earn money on their investments, like shares or unit trusts.

The main types of investment income which have income tax consequences are:

  • local and foreign interest
  • foreign dividends
  • interest from Real Estate Investment Trusts (REITs)
  • capital gains

The sale of investments (like shares) also triggers a capital gains tax event.

Dividends earned from local companies attract DWT (dividends withholding tax), but this is automatically withheld by the company who pays out the dividend, so there are no further tax obligations once you receive your net dividend (i.e after DWT).

The actual tax you pay depends on your own marginal income tax rate and the type and amount of investment income and capital gains you earn from your investments. The higher your marginal income tax rate, the more tax you will pay.

If you own investments, your financial institution should issue you a tax certificate (IT3b) which you must use to complete the investment section of your tax return. This will ensure that your taxable income is calculated accurately with the correct interest, foreign dividends and foreign tax credits included.

Local interest income

If you own bonds or have cash in the bank, then the interest you earn on this will be taxed. If you hold unit trusts then these often attract interest, which is taxable too. This interest income is subject to income tax and is taxed at your marginal tax rate.

Individual taxpayers enjoy an annual exemption on all South African interest income they earn, set by SARS every year. This interest exemption has remained unchanged for a number of years and for the 2026 tax year is set at R23 800 for individuals under 65 years old, and R34 500 for individuals 65 years and older. South African Retail Savings Bonds and any interest from the money in your Medical Savings Account (of your medical aid) can also be taxed.

You need to declare local interest (source code 4201) in the Investment Income section of your tax return.

Foreign interest income

If you earn foreign interest, you need to report the Rand equivalent amount to SARS. Unlike local interest, there is no exempt portion, however you will be able to deduct any foreign tax you pay.

You need to declare foreign interest (source code 4218) in the Investment Income section of your tax return, together with the foreign tax credit which was paid in another country (source code 4113).

Local dividend income

For equities (excluding listed property companies), dividends withholding tax (DWT) of 20% is withheld before it’s paid out or reinvested. Note that DWT is payable only on dividends paid out by the companies and is payable after the company has already paid 28% corporate tax on its net profits.

Foreign dividend income

South African residents that earn foreign dividends generally have to pay tax on those foreign dividends and declare them when submitting their South African tax return.

The tax paid on the foreign dividends depends on the amount and type of shares held in the foreign company.

In most cases, where the taxpayer holds less than 10% of the equity shares and voting rights in the foreign company, then the foreign dividend received will be taxed. The full amount of the dividend must be shown in the tax return, however SARS will allow a tax exemption which equates to 25/45 of the Rand value of the foreign dividend. If the taxpayer has paid foreign tax on the dividend, this must also be declared, and SARS will reduce the local tax by the foreign tax paid.

Where the taxpayer holds at least 10% of the equity shares and voting rights in the foreign company, then 100% of the foreign dividend will be exempt in the taxpayer’s hands.

Income from Real Estate Investment Trust (REIT)

The tax regime associated with listed property companies in the form of Real Estate Investment Trusts (REITs) is more complicated than other asset classes. REITs are taxed differently to other listed companies: they do not pay corporate income tax, and their investors do not incur DWT on the distributions they receive. Instead, investors pay income tax on the distributions they receive from these REITS at their marginal income tax rate.

You need to declare distributions from REITS (source code 4238) in the investment income section of your tax return.

The investment tax certificate (IT3b)

An IT3b is a tax certificate received from an institution like a bank or financial services company. It will be a summary of any interest dividends (both local and foreign) and REIT that you would have earned by having money invested with one or more of these places.

What about Capital Gains Tax?

A capital gains event is triggered only when you decide to sell (part or all of) your investments, like units in a unit trust. If the price of the units has risen since you invested, this increase in value is known as a capital gain, or a capital loss if the value has declined. Currently, an amount of 40% of this capital gain (not the total proceeds) is included in your annual taxable income – this makes the maximum effective capital gains tax rate for individuals 18%. How do we work this out? By taking the maximum 45% marginal tax rate for individuals and multiplying it by 40%, that’s how.

Note that individual taxpayers currently enjoy an annual capital gain exclusion of R 40 000.

Tax free savings account

South Africans are not very good at saving, for a number of reasons. With most people living near or below the breadline, it’s impossible to save when you’re more concerned with merely surviving. Combine this with our high levels of consumer debt, and little in the way of personal savings, and this means that many people become financial burdens on the government in the long run. This is why the government introduced tax free savings accounts in March 2015, as a way to encourage household savings among South Africans.

Since then, financial institutions have tried to get people on board with these savings accounts, promoting them heavily on the radio, TV and online, explaining to people that they are an accessible way to save. And because they offer a tax break to consumers, this year you’ll see them referenced on your annual tax return (ITR12).

What is a tax free savings account?

This savings account offered by financial institutions invests your money in a combination of financial products like unit trusts, bank savings accounts, fixed deposits and bonds.

So how is it different? The difference between it and other savings or investment accounts is that all returns (the interest, dividends or capital gains earned), will be tax-free in your hands. This means that you’re not liable to pay tax on the growth of your investment, or if you decide to withdraw from your account.

Are there limits to tax free savings accounts?

Annual and lifetime contribution amounts
There’s an annual contribution limit of R 36 000 for the 2026 tax year, as well as a lifetime limit of R 500 000. Once you’ve reached your lifetime contribution limit of R 500 000, you can’t make any more investments into your tax-free savings account, otherwise you will be penalised by SARS.

The annual contribution limitations for previous tax years:

  • R 30 000 for the 2016 and 2017 tax years
  • R 33 000 for the 2018, 2019 and 2020 tax years
  • R 36 000 for the 2021, 2022, 2023, 2024, 205 and 2026 tax years

No limit on number of accounts
Your annual limitation can be spread across as many savings accounts as you want, as long as you don’t invest more than R 36 000 in total in for the 2026 tax year (1 March to end February). If, for example, you’ve already contributed R 20 000 to one tax free savings account in that time period, you’ll only be able to invest up to R 16 000 in any others.

No carry over of annual contribution limit
Your annual limitation can’t be carried over to the next tax year – instead you simply forfeit any amount you didn’t use and are given a new annual limit to invest in a tax-free savings account. For example, if you’ve invested R 26 000 in the 2026 tax year, you can’t carry the R 10 000 over to the next tax year.

Contributing to a tax-free savings account for a minor
As a parent, it’s a good idea to open a tax-free savings account for your children, but you need to be aware that any contributions you make on their behalf count towards their annual and lifetime contribution limit.

Why should I take out a tax-free savings account?

Get tax free growth, even if you reinvest
The biggest advantage of a tax-free savings account is that your earnings on the initial investment are not taxed when you withdraw the funds. You can reinvest (or capitalise) your returns, and they don’t go towards your annual or lifetime contribution limit.

For example, if you invest R 36 000 for the 2026 tax year and receive a return on this investment of R 6 000 that you then re-invest, the total amount in the account will be R 42 000. But you’ll still be able to invest your full R36 000 the next year as the R 6 000 reinvestment doesn’t count towards your annual or lifetime limit.

Unlimited withdrawals (with conditions)
You can withdraw from your tax savings account any time, however any replacement investment amount is treated like a new contribution and will therefore count towards your annual and lifetime limits.

Say you withdraw R 36 000 from your tax free savings account, because you’re experiencing a temporary cashflow problem. A few months later (in the same tax year), you have a bit of spare cash again, so you deposit R 36 000 back into your tax free savings account. Provided that you haven’t made any other contributions for the year, this amount takes you right up to your contribution limit for the year, plus it’ll be added your overall lifetime contribution. If you’d already made a contribution in the tax year, this payment would have pushed you over your annual contribution level and SARS will penalise you (see below).

What happens if I exceed my contribution limit?

If you go over your annual or lifetime limit, SARS makes you pay a strict 40% penalty on the excess you contributed. You’ll need to pay this after assessment in the year that you exceeded the limit.

Say that in one tax year, you invest R 10 000 in a tax free savings account with one institution and R 30 000 in an account with another one, you will have contributed R 4 000 more than your annual limit of R 36 000. The penalty will therefore be 40% of this excess contribution (R 4 000 x 40%), which equals a R 1 600 tax penalty you’ll need to pay.

How do I report my tax free savings account on my tax return (ITR12)?

The financial institution holding your tax free savings account will issue you with a tax certificate called an IT3(s), which has all the details you need for your tax return like contributions, interest and dividends. Capture this information from your certificate in a new section in your tax return called Tax Free Investments
SARS is coming after company directors

SARS is targeting the directors of companies who fail to submit their tax returns.

The move forms part of SARS’s broader strategy to combat tax evasion and ensure that all corporate entities and their directors meet their tax obligations.

The agency previously relied heavily on administrative penalties and audits to encourage compliance.

However, the persistence of intentional non-compliance among some company directors has necessitated more drastic measures be implemented.

This new enforcement strategy aims to hold individuals vicariously accountable for the financial management of their companies, as directors have a fiduciary duty to ensure that their companies comply with tax laws.

Failure to do so not only undermine a healthy tax ecosystem but also places an unfair burden on compliant taxpayers.

Under South African law, it is a criminal offence for company directors to not submit their corporate income tax returns and those pertaining to payroll taxes and VAT.

The Tax Administration Act means that directors who fail to ensure the timely submission of their companies’ returns will face major penalties, such as fines and, in some instances, imprisonment.

The criminal summonses issued by SARS indicate the beginning of legal proceedings that could lead to prosecution.

If found guilty, directors could face imprisonment of up to two years per successful conviction of any criminal offence related to non-compliance.

Several high-profile cases involving directors have already occurred.

Public reaction to SARS’ compliance crusade has been mixed, however, many taxpayers and advocacy groups have welcomed the move, viewing it as a necessary step to ensure just and equitable treatment within the framework of our tax system.

They argue that stringent enforcement against non-compliant directors will deter others from similar misconduct and ultimately enhance the integrity of the tax regime.

However, some business leaders have expressed concerns about the potential for overreach and the impact on business operations. They urge SARS to balance enforcement with support, providing more guidance and resources to help companies in voluntarily meeting their tax obligations.

SARS’s issuance of criminal summonses is part of a broader initiative to strengthen tax compliance in South Africa, with the agency deploying its data analytics capabilities to identify non-compliant taxpayers efficiently and deploying more resources to audits

The agency has also been enhancing its data analytics capabilities to more effectively identify non-compliant taxpayers and deploy more resources to its audit and investigation teams.

That said, Commissioner Kieswetter has reiterated that while enforcement is necessary, SARS will engage with the business community to promote voluntary compliance.

SARS has indicated on many occasions that it aims to make compliance easy and cost-effective while making non-compliance difficult and costly.


SARS keeping an eye on international travel and high-end vehicles


The South African Revenue Service is desperate to extract as much money as possible from taxpayers, and the nefarious activities are in the taxman’s firing line.

Although many taxpayers expect minor repercussions such as fines and interest charges, a new protection strategy, with the help of the Hawks, South African Police Service (SAPS), and the National Prosecuting Authority (NPA), is becoming more aggressive over non-compliance.

Amid mounting pressure on tax collections and non-compliance, the entity is actively targeting taxpayers who fail to disclose their taxable income accurately.

The taxman’s efforts have resulted in record tax collection figures, with collecting R2.155 trillion in tax revenue for the fiscal year ended March – R10 billion more than the Treasury had even predicted.

One reason for the increase was the 8% growth in personal income tax (R651 billion), with SARS making a concerted effort to target citizens who avoid their tax obligations or do not submit their returns correctly under the willful non-compliance category.

The revenue office relies on personal information, AI and machine learning algorithms to identify and flag non-compliant taxpayers.

SARS looks at flight activity (such as frequent international travel) and luxury purchases (such as high-end vehicles or luxury vacations) and could execute a luxury audit to verify if an individual displays a lifestyle that does not match the tax return.

Through its specialist High Wealth Individual Unit and the Specialized Audit Unit, SARS has managed to achieve record tax revenue.

We have seen in recent reports of individuals being arrested and imprisoned, which is a serious warning that being non-compliant is a very dangerous place to be.

Over the 2023/24 fiscal years, SARS was successful in 94 of the 110 cases that were handed down, an 84% litigation success rate.

SARS offers a Voluntary Disclosure Programme (VDP) to individuals, companies, or trusts to voluntarily disclose and resolve their tax matters, as long as they are not under or expecting an audit or investigation from SARS or have reached a request for inflation from SARS.

Proactively rectifying tax defaults not only brings compliance relief but also significantly lowers the risk of penalties and legal repercussions.


AI enhancements: 2024 filing season

The South African Revenue Service (SARS) is fighting a war on non-compliance, and taxpayers shouldn’t think that they can hide any information from the taxman.

Individual taxpayers, provisional and non-provisional, will be able to file their annual tax returns from 15 July 2024.

With the enhanced efficiency propelled by SARS’ use of Artificial Intelligence (AI) data-driven compliance insights, “Open Season” on non-compliant taxpayers is year-round, but Filing Season presents a unique opportunity for SARS’ expert marksmen to step up.

Despite the examples of the rich flouting tax laws and ending up in jail, the average Joe should also keep in mind that they can end up in the same hot water.

The average person may not know that they have stepped on the wrong side of SARS’s war on non-compliance, with section 234 of the Tax Administration Act providing a list of actions and inactions which constitute criminal offences.

This list includes acts committed based on an absence of tax literacy, such as retaining specific documentary items or issuing an incomplete document to SARS.

On the flip side, failure to commit acts, such as the submission of a tax return or notifying SARS of a change in registered particulars, may also result in criminal charges being laid against you.

Whilst the listed offences range from the obvious, such as pretending to be a SARS official, to the seemingly unassuming, such as submitting erroneous statements to SARS, they all carry a liability, upon conviction, of a fine or a maximum prison sentence of 2 years.

Low- and medium-income earners often believe that they hide information from SARS, but the revenue service likely knows more about your finances than your family does.

SARS also has multilateral engagements, with automatic information exchanges with revenue collection agencies worldwide.

Although this information gathering capability has been tried and tested, the issue was a lack of manpower to effectively process and prosecute those guilty parties – the solution is SARS’ pilot AI project.

This AI capacity-bolstering technique has already been seen across SARS’ historic audit processes, where it is used to maintain thoroughness and accuracy while deriving data-driven insights almost instantaneously.

This move underscores a broader trend towards the integration of technology in tax administration, promising to revolutionize the way tax compliance is monitored and enforced.

If one finds themselves in SARS’s crosshairs over non-compliance, it is crucial that they make a timely response to SARS with all the correct supporting documentation.

Those who fail this first hurdle will also have made an incorrect disclosure to SARS. They will feel additional pressure when additional assessments are raised, or final demands are received for overdue tax debts.

The nail in the coffin is always the Understatement Penalties, capping at a bank-breaking 200% of the capital taxes due.

Medical Aid and Tax Deductions

The tax season dates are not yet announced. However, based on prior years, they are expected to be the following:

01 July 2024 to 23 October 2024: individual (non-provisional) taxpayers

01 July 2024 to 24 January 2025: provisional taxpayers


Here are the top 5 reasons why you should not skip filing your tax return this season:

  1. You miss out on your refund.

    A refund is money you overpaid on your taxes and it belongs to you. You can only get a refund if you file a return. Something as simple as claiming Medical expenses or working for less than 12 months of the tax year can trigger a tax refund, depending on your situation.


  1. You may not be able to borrow money.

    If you wish to borrow money in the form of a mortgage for a home, or a long-term loan of any kind in future, you may need a Tax Compliance Certificate. This can only be obtained if all your returns are up to date and filed appropriately.


  1. SARS might change their mind.

    If you normally submit, but this year you don’t, SARS could administer administrative penalties later on down the line for not being compliant, and no one wants that!


  1. You can’t access your retirement fund.

    Filing a tax return each and every year means that should you receive a payout from a fund at any stage, then you will not have any hassle in getting the money. If you retire or are retrenched, or just need to take money out of your fund early, you need to be tax compliant.


  1. A complete tax record stands in your favor.

    Having an unbroken filing record leaves SARS officials with no reason to suspect that you are hiding information from them. Filing a tax return means you are being a good citizen and contributing towards society.


Medical Expenses

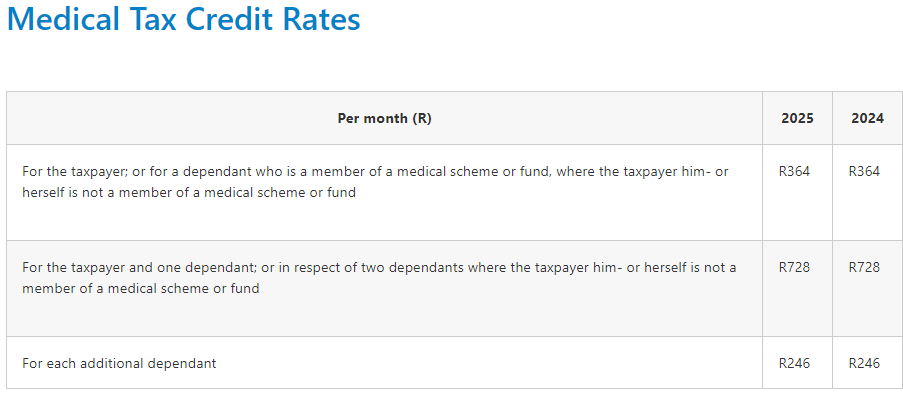
If you contribute to a Medical Aid, you will receive a fixed monthly tax credit for each member on your policy. SARS calls this rebate the Medical Schemes Fees Tax Credit – it is a flat rate per month (i.e. it doesn’t take your taxable income into consideration) and is a direct deduction off your tax liability. Note that the tax credit applies only to registered medical aid funds – medical insurance or GAP cover does not count.

Make sure that you have a tax certificate from your medical aid provider as support for this tax credit. They generally send these out on email before filing season opens.

If you have ‘qualifying’ medical expenses, which were not reimbursed by the medical aid, you should also include these in your tax return because you may qualify for an ‘additional medical expenses tax credit’. Qualifying medical expenses includes all consultations with medical practitioners as well as doctor prescribed medication. SARS applies a complicated formula to work out whether you spent enough to qualify for an ‘additional medical expenses tax credit’.

Remember to ensure you have proof for every single medical expense you paid for over and above your medical aid cover with invoices and / or detailed receipts.

Your medical scheme provider is supposed to send your tax certificate to you by email or post by July, but if they have not done so, you can ask for it directly.

A tax credit is a non-refundable rebate. This means that a portion of your qualifying expenses, in this case medical related spend, is converted to a tax credit, which is deducted from your overall tax liability (the amount of tax you have to pay SARS). You can’t carry any unused credit over to the next tax year and it won’t ever result in a negative amount or standalone refund from SARS.

This means that if you don’t earn an income, but do contribute a medical aid, you can’t claim the medical credit.


Who SARS Considers as Dependents for Medical Expense Claims

SARS sees the following as dependents:

  • A spouse (husband or wife)
  • A child and the child of a spouse (e.g. son, daughter, stepchild or children, adopted child or children) who was alive during any part of the year of assessment, and provided that on the last day of the year of assessment he / she was unmarried and:
    • a minor, i.e. under the age of 18, or
    • under 21 years of age, but partly or entirely dependent on you for maintenance and not yet liable for normal tax themselves, or
    • under 26 years of age, but partly or entirely dependent on you for maintenance, not yet liable to pay normal tax themselves and a full-time student at a publicly recognized educational institution such as a university or Technikon
  • Any other member of your family who relies on you for family care and support (e.g. mother, father, sibling, mother or father-in-law, grandparent or grandchildren)
  • Any other person recognized as a dependent in terms of the rules of a medical scheme or fund
  • Proof of above payments will be required to claim the medical expenses if the dependent is not directly on your medical aid, however you do pay for their medical expenses


What are Qualifying Medical Expenses for Tax?

Examples of qualifying medical expenses are any amounts that were paid by you, as the taxpayer, during the year of assessment:

  • For professional services rendered and medicines supplied by a registered medical practitioner, dentist, optometrist, homeopath, naturopath, osteopath, herbalist, physiotherapist, chiropractor or orthopedist to you or any of your dependent(s)
  • To a nursing home or hospital, or any duly registered or enrolled nurse, midwife or nursing assistant (or to any nursing agency in respect of the services of such a nurse, midwife or nursing assistant) in respect of the illness or confinement of the person or any dependent of the person
  • For medicines prescribed by a registered medical practitioner and acquired from a pharmacist
  • Medical expenses incurred and paid outside South Africa
  • It’s important to note that “over the counter” medicines – such as cough syrups, headache tablets or vitamins don’t qualify as medical expenses – unless specifically prescribed by a registered medical practitioner and acquired from a pharmacist.


SARS is strict on the definition of a qualifying disability. According to the Income Tax Act, a disability is:

A moderate to severe limitation of that person’s ability to function or perform daily activities, as a result of a physical, sensory, communication, intellectual or mental impairment if the limitation:

  • Has lasted or has a prognosis of lasting more than a year; and
  • Is diagnosed by a duly registered medical practitioner in accordance with the criteria prescribed by the Commissioner

In order to benefit from the full disability-related medical expenses provisions, you’ll need to have an ITR-DD (confirmation of diagnosis of disability form for an individual taxpayer) form completed by a registered medical practitioner.

Click on this link https://www.sars.gov.za/wp-content/uploads/SARS_ITR-DD_PD_E_v2023.13.00.pdf or email us at teresa@worldwidetax.co.uk for a copy of this form


What supporting documents do I need for SARS?

If you do claim medical credits as a result of paying medical aid for a dependent, where you are not the main member of the medical scheme, then it is almost certain that SARS will audit you. In this case, be sure you have the following:

  1. The medical aid tax certificate in the financial dependent’s name,
  2. Proof of payment to the medical aid (bank statements for that tax year)
  3. Letter explaining why this dependent is currently financially relying on you. (Please find below letter template)


Medical Aid contributions paid on behalf of a dependent

If you are claiming medical aid tax rebates on your personal return, but you are not the main member on the medical aid, we will need below related form completed and returned with your 2024 tax documents. You are only allowed to claim the medical aid tax rebates provided no one else is claiming this on their own returns.


Date
Taxpayer’s Full Name
Address

To Whom It May Concern,

Subject: medical aid contributions paid on behalf of a dependant

This letter serves to confirm that I, ________________________(taxpayer’s full name), __________________________(ID number) am contributing to a medical aid on behalf of _______________________________(name of dependant),___________________(ID number). He/she is/is not  financially dependent on me and I am currently financially assisting due to: ________________________________________________________

I have been making medical aid contributions on behalf of my dependant for the following months:

_______________________________

Monthly contributions:             R_________

Total annual contributions:      R_________

Tax year:                                     __________


Please see proof of payments attached.


______________________
Name
Relationship status e.g. Father
Telephone
Email


Medical Aid Monthly Rebates:

How to get your money out of South Africa

Many South Africans find themselves considering opportunities abroad, but moving their funds abroad can be a confusing process.

A comprehensive understanding of ceasing tax residency and exchange control regulations is essential in moving abroad.

Financial emigration is the formal process for relocating abroad permanently, and it requires obtaining a non-resident tax status letter from the South African Revenue Service (SARS).

South Africa’s tax system is residence-based, meaning residents pay taxes on global income.

Transitioning to non-resident tax status involves formal declaration to SARS and ongoing compliance with tax and exchange control regulations.

The SARS notice confirms cessation of tax residency and specifies the date.

Once deemed a non-resident for tax purposes, individuals are only required to declare and pay taxes on income earned within South Africa and adhere to regulatory requirements set forth by SARS and exchange control authorities.

In addition, South Africans emigrating need to be cognisant of South Africa’s exchange control regulations, overseen by the South African Reserve Bank (SARB).

These regulations are crucial for managing capital flows in and out of the country.

The following has to be considered in terms of the nation’s exchange control regulations:

  • Changing tax residency status requires corresponding adjustments to banking status as per SARB mandates. When one is no longer a tax resident in South Africa, individuals must update their banking status by converting bank accounts to non-tax resident status.
  • All transfers are subject to exchange control approval and clearance by the SARS. Transferring South African assets upon ceasing tax residency may not be straightforward. For instance, cashing out retirement policies after maintaining non-tax resident status for at least three consecutive years necessitates the authorized dealer verifying the source and available Tax Compliance Status (TCS) PIN.
  • The treatment of fund transfers depends on the nature of funds, whether classified as capital or income. For those transferring proceeds from capital assets sale, they need to provide an AIT TCS PIN from SARS to authorized dealers.

South African residents can transfer up to R1 million out of South Africa annually through their Single Discretionary Allowance (SDA) without SARS’s clearance.

Anything above the limit will require an Approval International Transfer (AIT) TCS PIN from SARS.

Non-residents, on the other hand, can transfer up to R1 million as a Non-Resident Travel Allowance (TA) in the year in which they formally cease tax residency.

However, this is a one-time allowance and cannot be used in the following years.

Moreover, individuals can no longer be eligible to make use of the SDA when tax residency is ceased.

Therefore, all capital transfers out of South Africa, except for specific exceptions, need SARS approval through means of obtaining an AIT TCS PIN.

It is important to distinguish between TA and SDA, as any remaining SDA balance can’t be used under TA.

For any transfers exceeding R10 million, approval from the Financial Surveillance Department of SARB is additionally required.

This triggers a comprehensive Risk Management Test, including tax status verification, assessment of funds’ source, and compliance with anti-money laundering and counter-terrorism financing requirements.

You can follow us on our for live updates

Link:

SARS is not messing around – with jail time and fines

South Africans not complying with the nation’s tax laws face serious prison time.

In a recent case before the Johannesburg High Court, a VAT fraud syndicate was sentenced to a cumulative 205-year prison term.

The individual sentences ranged from 5 to 65 years, with fraudulent VAT claims from SARS estimated at over R200 million.

The  defines a “serious tax offence” as the following:

“Serious tax offence means a tax offence for which a person may be liable on conviction to imprisonment for a period exceeding two years without the option of a fine or to a fine exceeding the equivalent amount of a fine under the Adjustment of Fines Act, 1991 (Act 101 of 1991).”

In practice, a “tax offence” can take the form of any contravention of a tax act, and including the criminal offences specifically listed and in relation to taxpayer non-compliance.

This includes:

  • Submission or issuance of false documentation/certification;
  • Obstruction of a SARS Official in carrying out their duties;
  • Failing to notify SARS of a change in registered details; and
  • Failing to submit a tax return or retain sufficient records.

Although strong statements on non-compliance are more public than ever before, criminal protection has long been on the cards for the revenue collector.

Since the SARS and NPA team-up, successful prosecutions have increased for individuals and companies, with punishments ranging from account-draining fines to prison sentences.

SARS is now increasing its collection power through aggressive collection tactics, including salary garnishes, Sheriff callouts, and taking money directly from business and personal accounts.

SARS Commissioner Edward Kieswetter said that the organization will do its best to make it easy and seamless for taxpayers to transact with the organisation and be compliant in their tax affairs.

For the non-compliant, it hopes to make life very difficult and costly.


SARS double-tax warning for South African expats

The South African Revenue Service’s (SARS) inefficiencies are leaving expats in limbo, contending with double taxation unnecessarily.

South African expats abroad face increasingly turbulent waters regarding taxes.

Many expats depend on Double Tax Agreements (DTAs) to prevent double taxation on the same earnings.

However, there seems to be a blind spot from a tax administration standpoint.

Concerns are growing about applications submitted to SARS, pointing out systemic inefficiencies which are causing delays in crucial decisions.

If an individual is a tax resident in another country but a tax non-resident in South Africa, they may be eligible for relief from South African tax on their South African pensions and annuities.

South Africa has 22 DTAs that provide for this relief, including agreements with the UK and New Zealand, among others.

However, it is important to note that a DTA does not automatically apply, and the taxpayer must claim the relief measures.

The process of claiming DTA relief can be problematic.

If an individual has been a tax non-resident for three or more years, they can cash out their South African retirement interests as a lump sum payment.

This means that they can withdraw all their retirement savings at once.

However, if an individual has previously withdrawn their retirement savings as a lump sum and now receives an annuity, they must withdraw the funds gradually at a maximum rate of 17.5% per year.

For instance, if someone is retired and has already started withdrawing from their retirement savings, they are not allowed to withdraw the entire amount in one lump sum when they relocate overseas.

It is important to note that a lump sum withdrawal from a retirement fund can only be made after SARS has issued a directive on how much tax should be withheld.

However, it is not possible to claim DTA relief at the directive application stage to confirm that no tax will be withheld.

This means that many people who have previously made a lump sum withdrawal were not aware that they qualify for DTA relief.

Even those who are aware will have to wait until they file their next return and then lodge a dispute against the tax withheld.

This may not be a problem for some expats, but for many others, it means that they may potentially have to deal with double taxation, even if only temporarily.

For expats whose retirement interests have already been annuitized, there is a route to obtain a Nil tax directive from SARS.

To apply for an RST01 directive, one needs to complete an application form, get it signed and stamped by the revenue authorities in their country of residence, and send it to SARS.

However, many expats who apply through this route never receive a response.

This backlog not only affects business operations but also undermines trust in the tax system.

Claiming DTA relief from tax on annuities in South Africa is theoretically possible, but in reality, it is difficult to get an actual outcome from SARS on the matter.

This has caused mounting confusion and frustration among taxpayers, especially expats.

The lack of transparency and consistency in the SARS’ application process and the absence of any structured timeline for processing these applications exacerbates the situation.

Taxpayers are left in limbo for extended periods, often indefinitely.

SARS knows what’s happening in your bank account

Sharpening its revenue collection tools has seen the South African Revenue Service (Sars) require that several taxpayers explain why the revenue declared in their income tax return does not match the deposits detected in their bank accounts. Unsatisfactory answers have led to estimated or additional assessments and even hefty penalties being imposed. Sars has taken to augmenting taxpayer revenue.

Revenue augmentation is a process of comparing what a taxpayer declared as revenue in [their] tax return to the amounts actually deposited into taxpayer’s bank accounts.

If a taxpayer declared R1 million but the deposits suggest revenue of R10 million, they must explain why Sars should not raise an additional assessment to tax the “undeclared revenue”.

Sars has had access to taxpayers’ information from third-party data providers such as banks and other financial institutions since 2012.

As you can imagine that is a lot of data. They have lately improved their capacity and systems to process this data much more efficiently. That is why we are now seeing an increased utilisation of the data to verify information that is being declared [in relation] to what is being received from third-party service providers.

SARS has increased audit focus on individual taxpayers since January. These variances are huge, so it does make sense for Sars to pursue cases where they are likely to recover undeclared revenue

Taxpayers must realise that Sars is continuously seeking new, better and more efficient ways in which to obtain a “360-degree view” of taxpayers’ affairs.

This includes a review of movements in their bank accounts, their world-wide income and other assets in or outside SA.

If the taxpayer does not respond or does not supply adequate reasons why the deposits have not been declared, or that they relate to loans or inter-account transfers – or potentially from other non-taxable income – then Sars will raise these assessments.

The revised assessments can be challenged through the relevant dispute mechanism procedures. However, as we know these procedures take time, effort and can be costly

The tax law places the burden of proof on taxpayers. Sars may require a taxpayer to reconcile amounts on a line-by-line basis, and explain on a line-by-line basis – with evidence – why a particular deposit does not stand to be included in their gross income.

It may take a taxpayer weeks to fend off additional assessments. If they do not go through this extensive line-by-line exercise a likely outcome is that Sars will collect or try to collect the amount it has assessed, despite these assessments often – but not always – being ultimately incorrect.

Taxpayers who are currently the focus of Sars’s attention are the ones who are unlikely to respond when questions are asked about deposits in their bank accounts, or by the time Sars gets around to them there will be no assets in their name or money in the bank account.

There are instances of downright non-compliance and taxpayers are “ultimately held accountable for the correctness of their tax returns.

Once Sars has alerted the taxpayer to the discrepancy they have to engage with Sars.

Taxpayers should also note that if Sars raises an estimated assessment they will not be able to object to the assessment.

This means they cannot, in law, request reasons for the assessment, nor can they, in law, ask for payment of the often-overstated assessment to be suspended pending a challenge against these assessments

Taxpayers must distinguish between an original, additional and estimated assessment.

Nzimande advises taxpayers to invest time to understand and review the information declared on their tax returns, even if they have a professional that assists with the filing of their returns.

If there are issues with the declarations, the taxpayer is the one who will ultimately be held accountable.

Worldwide Tax Solutions Newsletter: Tax Free Savings Accounts

What is a Tax Free Savings Account?

Basically it’s a type of savings account offered by financial institutions that invests your money in a combination of financial products such as unit trusts, bank savings accounts, fixed deposits, bonds, etc.

The difference between this and other savings or investment accounts is that all returns, i.e. the interest, dividends or capital gains earned, will be tax free in your hands.

This means that you’re not liable to pay tax on the growth of your investment, nor if you decide to withdraw from your account.

A tax free savings accounts- just means it is tax free, it is not a tax deduction, therefore it will not be used as a deduction to bring your taxable income down

Are There Limits to Tax Free Savings Accounts?

There’s an annual contribution limit of R36 000 per tax year, as well as a lifetime limit of R500 000. Once you have reached your lifetime contribution limit of R500 000 no further investment in a tax free savings account will be allowed.

 No limit of number of accounts

The annual limitation can be spread across as many savings accounts as you wish, provided you don’t invest more than R36 000 in total for the tax year (1 March to end February).

So if, for example, you’ve already contributed R10 000 to one tax free savings account for the period, you’ll only be able to invest a maximum of R26 000 to any others.

No carry over of annual contribution limit

The annual limitation can’t be carried over to the next tax year, you simply forfeit any unused amount and are given a new annual limit of R36 000 to invest in a tax free savings account.

For example, if you’ve invested R26 000 for the tax year, you can’t carry the R10 000 over to the next year.

Contribution to a tax free savings account for a minor

As a parent, you’re able to open a tax free savings account for your child(ren), but you need to be aware that any contributions you make to this account on their behalf counts towards their annual and lifetime contribution limit.

What are the Benefits of a Tax Free Savings Account?

Tax free growth, even if you reinvest

The critical advantage of a tax free savings account is that your growth or earnings on the initial investment are exempt from tax on withdrawal.

You’re able to reinvest (or capitalize) your returns and they don’t count towards your annual or lifetime contribution limit.

For example, if you invest R36 000 for the year and receive a return of investment of R2 000 that you re-invest, the total amount in the account will be R38 000, yet you’ll still be able to invest your full R36 000 the following year as the R2 000 reinvestment doesn’t count towards the annual or lifetime limit.

Unlimited withdrawals, with conditions

You’re free to withdraw from your tax savings account at any time you wish, however any replacement investment amount is treated as a new contribution and will therefore count towards your annual and lifetime limits.

Let’s pretend you withdraw an amount of R36 000 from your tax free savings account because you’re going through a short-term cashflow issue.

A few months later, in the same tax year, you come into a little money and so you deposit R36 000 back into your tax free savings account.

Provided you haven’t made any other contributions for the year, this amount takes you to your contribution limit for the year, plus it’ll be added your overall lifetime contribution.

If you’d already made a contribution in the tax year, this payment would have pushed you over your annual contribution level.

What Happens if I Exceed the Contribution Limit?

If you exceed your annual or lifetime limit, SARS imposes a stiff 40% penalty on the excess contributed.

This will be payable on assessment in the year you exceeded the limit.

For example, if in one tax year, you invest R20 000 in an account with one institution and R20 000 in an account with another, you will have contributed R4 000 more than the annual limit of R36 000.

The penalty will therefore be 40% of the excess contribution (R4 000 X 40%), giving you an R1 600 tax penalty to pay.

How Do I Report on My Tax Free Savings Account on My Tax Return (ITR12)?

The financial institution holding your tax free savings account will issue you with a tax certificate called IT3(s), which contains all the details you need for your tax return, e.g. contributions, interest, dividends, etc.

You can follow us on our for live updates

Link: